Free Shipping on Orders of $75 or more.
Sell Books in Your Shopify Store
Adding book to your cart
Report copyright infringement
by Karin Mautner (Author)
The effective numerical treatment of Black-Scholes equations is among the key issues in mathematical finance. The most important strategy for pricing American options relies on deterministic evolutionary variational inequalities on unbounded domains. This book provides the requisite mathematical background for the numerical treatment in weighted Sobolev spaces. The main focus is on the numerical analysis including a priori and a posteriori error estimates for finite element methods, and the effective simulation based on the design of adaptive mesh refinement algorithms. Numerical experiments that illustrate the advantage of this approach conclude this book, which is intended for graduate students and researchers in the area of mathematical finance and numerical analysis.
No books in the cart.
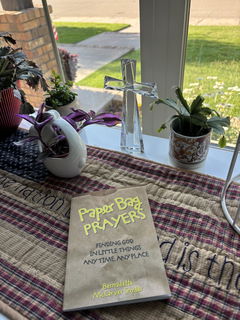
A small yet very thoughtful devotional book. A beautiful way to promote seeing God everyday in everything.
It’s the best. Worth every penny.
buen libro para dar los primeros pasos para aprender inglés
The book was bent in the top corner but overall i love it!
Great feel yum yum